More homeowners are exhibiting financial distress, the latest housing market trends reveal.
Though it rose only slightly from August by three basis points, the number of loans in forbearance increased to 0.34% as of September 30, according to the Mortgage Bankers Association’s (MBA) Loan Monitoring Survey.
The MBA estimated that 170,000 homeowners were in forbearance plans at the end of September, increasing for the fourth consecutive month.
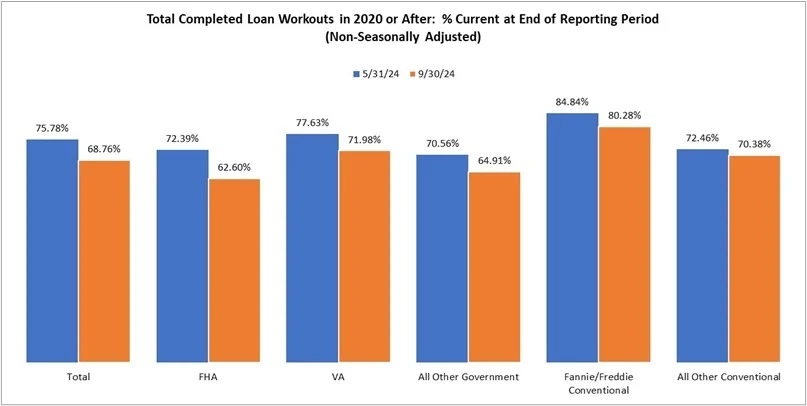
“Since May 2024, Ginnie Mae loans in forbearance have increased by almost 40 basis points, compared to six basis points for portfolio and PLS loans and three basis points for Fannie and Freddie loans,” MBA Vice President of Industry Analysis Marina Walsh pointed out. “We are seeing some weakening in loan performance, particularly among government products. Overall government loan performance reached a new low for the year in September. In addition, the share of government post-forbearance workouts that are current dropped considerably over the past four months. These trends indicate that some homeowners are exhibiting signs of distress – whether because of economic hardships, natural disasters, or other reasons.”
According to the survey, 70.4% of borrowers stated they are in forbearance for reasons such as a temporary hardship caused by job loss, death, divorce, or disability. Another 25.9% are in forbearance because of a natural disaster. Only 3.7% of borrowers are still in forbearance because of COVID-19.
Mortgage servicers have provided forbearance to approximately 8.3 million borrowers since March 2020, according to MBA estimates.
The share of Fannie Mae and Freddie Mac loans in forbearance remained the same as the previous month at 0.13%, while Ginnie Mae loans in forbearance increased by 10 basis points to 0.76%, and the forbearance share for portfolio loans and private-label securities (PLS) increased two basis points to 0.37%.
The Federal Housing Finance Agency's (FHFA) latest Foreclosure Prevention and Refinance Report showed mortgage forbearances and serious delinquencies were at historic lows through Q2 2024. Foreclosure starts fell 7% from the first quarter, while third-party and foreclosure sales declined 7.4%. Third-quarter data has not been released yet.
The MBA tracked loans in forbearance by stage, reporting that 65.5% of total loans in forbearance this September were in the initial forbearance plan stage, while 20.5% were in a forbearance extension. The remaining 14% were forbearance re-entries, including re-entries with extensions.